If financial advice leaves you poorer, the first question is not always “Which investment should I buy?” It may be “Who benefits when I act?”
Where Are the Customers’ Yachts? is Fred Schwed Jr.’s humorous, skeptical look at Wall Street, speculation, securities, and the distance between the industry’s confidence and the customer’s outcome. Its lasting value is not a portfolio formula. It is a prompt to examine incentives, costs, uncertainty, and the difference between activity and progress.
This article gives a practical summary and a cautious modern application. The seven lessons are a Wealthy I AM editorial synthesis, not a claim that Schwed presented this exact numbered framework. The book was originally published in 1940, so current product, tax, regulatory, and household decisions require current sources.
What is Where Are the Customers’ Yachts? about?
Open Library identifies the work as Where Are the Customers’ Yachts?, also titled A Good Hard Look at Wall Street, by Fred Schwed Jr. Its catalogued subjects include investments, speculation, stocks, Wall Street, and the securities industry. That supports the book’s broad satirical and skeptical subject, but a catalog record is not a substitute for checking every anecdote, argument, or historical detail in the edition you read.
The title’s question works as an incentives test. If brokers, advisers, fund managers, publishers, or product providers can earn money when customers trade, borrow, subscribe, or chase a fashionable idea, what durable value is the customer receiving? The question does not prove that every financial professional or product is harmful. It asks the investor to investigate the arrangement before mistaking confidence for evidence.
Who may benefit from the book?
The book may suit readers who feel pressured to trade, cannot explain what they own, or confuse a persuasive market story with an investment thesis. Experienced investors may appreciate its reminder that expertise and certainty are not the same thing.
It is not a current portfolio, tax plan, or personalized recommendation. Pair its historical satire with current authoritative information and advice suited to your circumstances.
Seven practical lessons inspired by Schwed’s skepticism
1. Ask who gets paid when you act
Before following a recommendation, identify the business model behind it. Is someone paid through a commission, spread, management fee, performance fee, subscription, referral payment, or another charge? Compensation can support a legitimate service; disclosure alone does not make a service good or bad. It gives you a question to investigate.
Try this: write down the provider, service, visible costs, and costs you still need to verify. If you cannot explain the arrangement in plain language, pause before committing money.
2. Treat confidence as presentation, not proof
A polished forecast is still a forecast. A strong track record may reflect skill, favorable conditions, luck, or selection effects. Healthy skepticism means requesting evidence, not automatically assuming the opposite of what a salesperson says.
Try this: for a proposed investment, write the thesis, supporting evidence, what could invalidate it, and what information is missing. Keep uncertainty visible.
3. Count friction before admiring a return
Friction is everything that reduces what you keep: fees, transaction costs, taxes, bid-ask spreads, financing costs, and the value of your time. The effect depends on the product, account, jurisdiction, and behavior, so this is a decision framework rather than a return calculation.
Try this: compare the total expected cost of an approach with a simpler alternative. Ask whether extra complexity has a clearly described purpose.
4. Separate investing from entertainment
Market activity can be exciting without being productive. Buying and selling may create a feeling of control while making a portfolio harder to monitor and more exposed to mistakes. Long-term investing requires a process for risk, diversification, liquidity, and time horizon—not a constant stream of opinions.
Try this: define the job of each holding or account. If you cannot state its role, such as liquidity, diversification, income, or long-term growth, review it before adding more.
5. Prefer a process you can repeat
A clever idea that cannot be explained, monitored, or repeated is fragile. A repeatable process might include a written goal, time horizon, asset-allocation policy, rebalancing rule, and review schedule. The right process differs by person; the value is making decisions before emotion takes over.
Try this: create a one-page investment policy. Include what you are trying to fund, the risks you can and cannot accept, when you will review the plan, and which events justify a change.
6. Let humility improve your downside planning
Skepticism matters most when a forecast is wrong. Downside planning can include an emergency reserve, limited leverage, appropriate diversification, liquidity checks, and a decision about what evidence would make you reduce or exit a position. None of these removes investment risk.
Try this: describe a bad-but-plausible outcome for each major financial decision and the safeguard that would keep it from becoming a household crisis. Do not borrow or invest money needed for near-term obligations without understanding the risk.
7. Judge advice by the customer outcome, not the adviser story
An adviser can sound intelligent, and a product can have a compelling history, without fitting your goal. The relevant questions are whether the recommendation is understandable, affordable, suitable to your time horizon, and consistent with your broader plan. No single metric settles suitability.
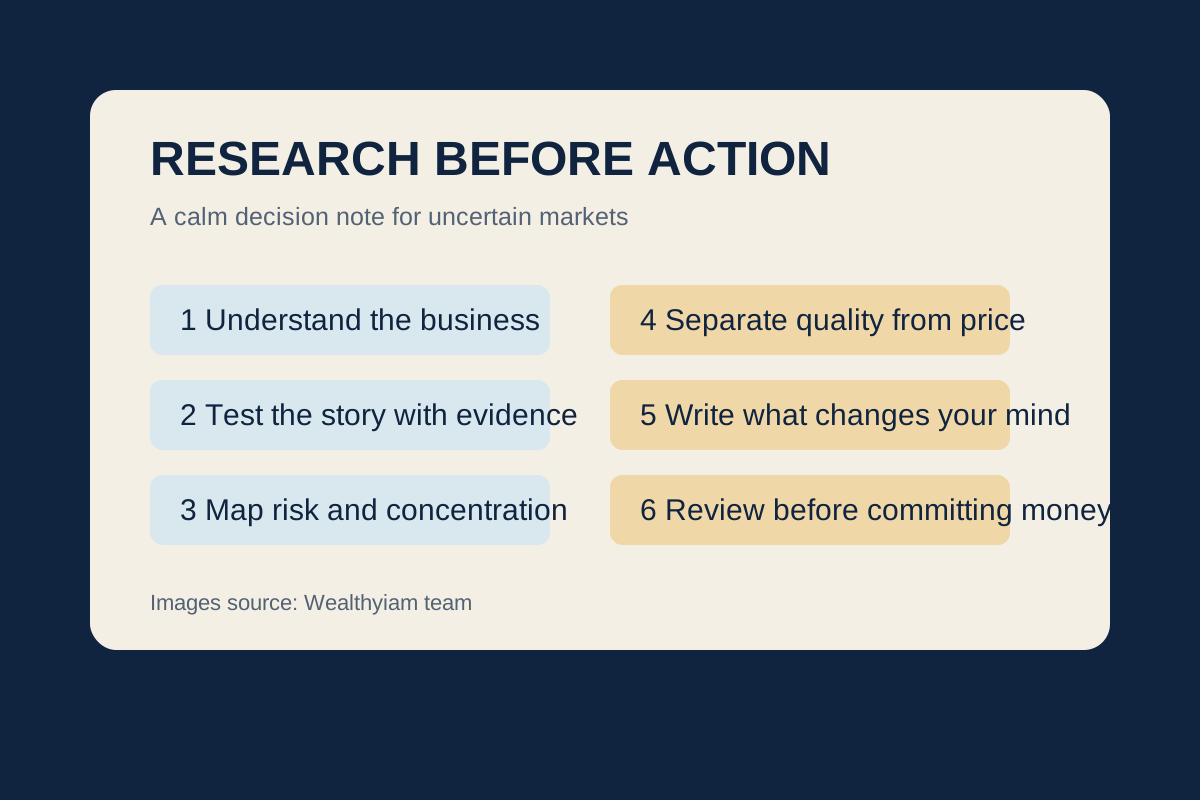
Try this: before agreeing, ask: What problem does this solve for me? What are the total costs? What are the main risks? What simpler option should I compare? Save the answers.
A practical 30-minute customer-first review
Use this as general education, not as a buy-or-sell signal.
- Name the goal. Put the time horizon beside it.
- List the product and provider. Record who supplies it and how each party is compensated.
- Map the costs. Look for management expenses, commissions, spreads, account charges, taxes, penalties, and borrowing costs. Mark unknowns instead of guessing.
- Write the risks. Note what can lose value, how quickly you may need the money, and whether leverage or concentration could amplify a loss.
- Compare a simpler baseline. This is not a recommendation; it tests whether complexity is earning its place.
- Set a decision rule. Choose what evidence would change your mind and when you will review the decision.
Hypothetical illustration: a busy investor and an expensive story
Suppose an investor is offered a complex product described as a way to keep up with the market. The investor does not know the total cost, cannot state the downside, and has not checked whether the money is needed within three years. A customer-first response is not automatically “buy” or “reject.” It is to pause, obtain the documents, clarify compensation and liquidity, compare alternatives, and check the decision against the household plan.
This is a hypothetical process example, not a forecast or a claim about any named provider or investment.
Mistakes to avoid
Becoming cynical about every professional
A warning about incentives is not proof of universal bad faith. People may pay for planning, research, execution, custody, or tax-related services because those services can be useful. Evaluate the service, conflicts, costs, and fit.
Treating satire as a portfolio strategy
A memorable critique does not tell you how much cash to hold, how to diversify, or which account is appropriate. Pair the book’s question with current authoritative information and, where appropriate, qualified professional advice.
Assuming low cost means low risk
Costs matter, but a cheap asset can still be volatile, illiquid, concentrated, or unsuitable for a goal. Consider both friction and risk.
Replacing research with distrust
“Everyone is wrong” is not due diligence. Read primary documents, understand what you own, check assumptions, and document uncertainty.
Ignoring taxes, law, and personal circumstances
Account rules, tax treatment, consumer protections, and suitability standards vary by jurisdiction and can change. This article is not individualized tax or legal advice.
Frequently asked questions
Is Where Are the Customers’ Yachts? a beginner investing book?
It can be a beginner-friendly prompt for questioning incentives and market stories, but it is not a complete investing curriculum. New investors still need current education on goals, emergency savings, diversification, fees, account rules, and risk.
Does the book say investors should avoid Wall Street?
The available bibliographic evidence supports a skeptical examination of Wall Street and investment advice, not a blanket instruction that every financial service is harmful. Read the satire as an invitation to investigate incentives and outcomes.
Can these lessons identify winning investments?
No. They can improve the questions you ask, but they do not predict returns or remove uncertainty. No investment outcome is guaranteed.
What is the first step I can take today?
Choose one account or product you already own. Write its purpose, total cost, main risk, liquidity, and provider compensation. Mark anything you cannot verify, then gather the governing documents before making a change.
Keep the book question and add your own evidence
Where Are the Customers’ Yachts? offers a durable question: when money changes hands in the financial system, who benefits, and how can the customer tell? The useful response is neither blind trust nor blanket distrust. It is a calmer process: clarify the goal, expose the incentives, count the friction, understand the downside, and compare the recommendation with a simpler baseline.
That is Wealthy I AM advice, not a quotation or guaranteed result from Schwed’s book. If you want one low-risk next step, complete the 30-minute review for one holding and keep a written record of what you still need to verify.
> General education notice: This article discusses a book and a decision-making framework. It is not individualized financial, tax, legal, or investment advice. Investing involves risk, including possible loss of principal.
Sources and further reading
- Open Library work record: Where Are the Customers’ Yachts? by Fred Schwed Jr. — bibliographic identity, title, author, subtitle, subjects, and edition context.
- Open Library Covers API image source — cover provenance for the supplied image; reuse rights must be checked before publication.